For a homeowner, an icy walkway is a bad morning and a bruised elbow at worst. For a business, it is a legal exposure that can dwarf the cost of a whole winter of clearing. The moment a customer, a delivery driver or an employee slips on your property, the questions begin, and the first one is always the same. When was this surface last cleared and treated? A documented snow removal plan is the difference between a confident answer and an expensive silence.
This is the part of commercial winter that owners underestimate until it is too late to fix, and it is almost entirely preventable with a little planning before the season turns.
Why Liability Changes Everything for a Business
A residential slip is a private misfortune. A commercial slip is a claim, and it lands on the property owner or occupier, who carries a duty to keep the premises reasonably safe. In our climate, reasonably safe means actively managing snow and ice throughout every event, not clearing once and hoping. That duty does not pause overnight, on a weekend, or over a holiday, which is exactly when a lot is least supervised and when many falls happen.
The financial stakes are what make a snow removal plan non negotiable for a business rather than a nicety to arrange when time allows. A single serious claim can exceed the cost of years of professional clearing, and the reputational damage of an unsafe lot is harder still to price. This is why commercial winter work is a genuinely different service from residential, a distinction we treat seriously across our snow removal operations rather than a matter of simply doing the same job at a larger size.
Documentation Is the Real Protection
Clearing the lot is only half of what a business is paying for. The other half is the record proving it was cleared. A serious snow removal plan logs everything, the time of each service, the conditions on site, the quantity and type of material applied, and photographs of the finished lot. When a claim arrives months later, that log is the defence.
Without documentation, a business is left arguing from memory against a specific allegation, which is a losing position. With it, the owner can show precisely when the surface was serviced and treated relative to the incident. This record keeping is a large part of what separates a commercial contractor from someone who merely owns a plow, and it is worth confirming in detail before signing. A contractor serving businesses across these communities should be able to explain their logging without hesitation.
What a Commercial Snow Removal Plan Includes
A proper plan is built around the site rather than the calendar. It specifies a trigger depth at which clearing begins automatically, without anyone making a call, and it defines response times keyed to when staff and customers arrive. It designates where snow will be stacked so it does not consume half the parking lot by February or block sightlines at the exits, and it plans for hauling that snow away entirely on tighter urban sites where there is simply nowhere to put it.
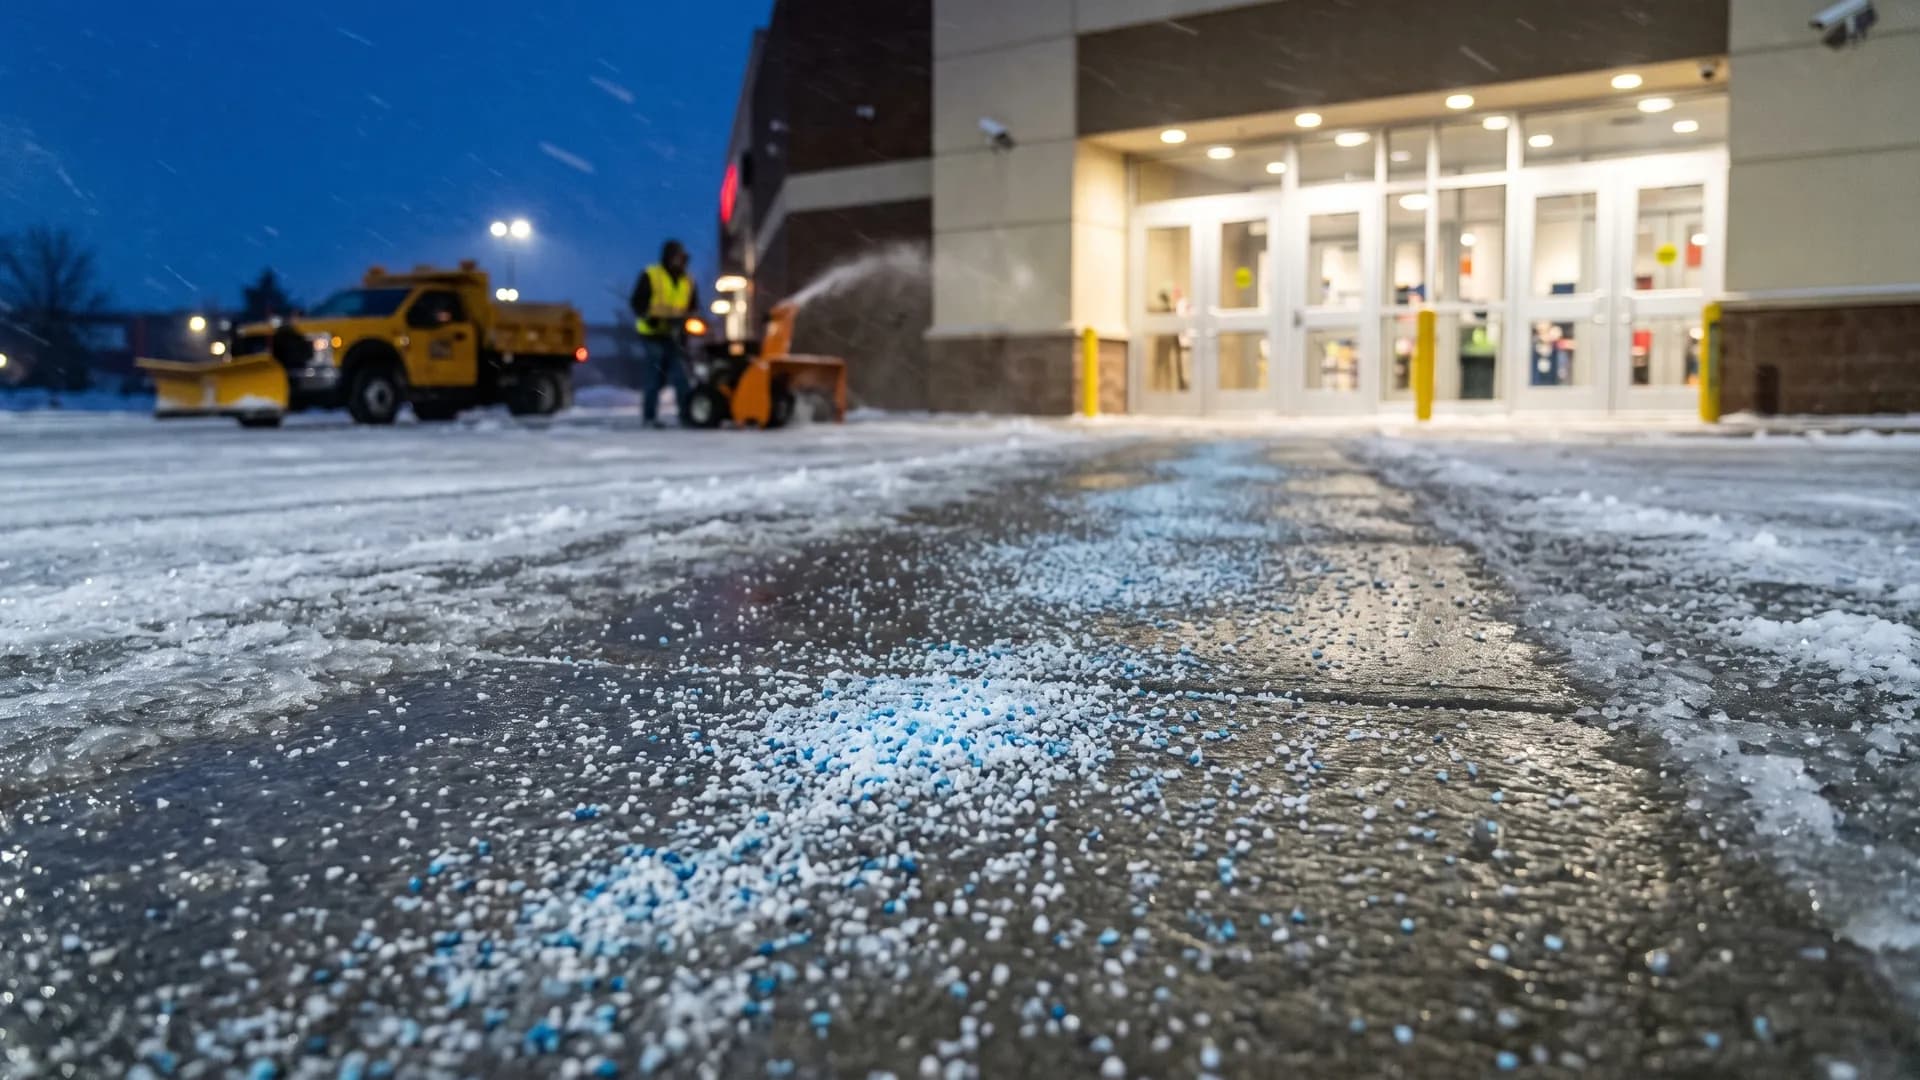
Salting and traction control run on their own schedule within the plan, often applied several times through a single event, before the snow bonds, again after clearing, and once more if an overnight refreeze threatens a wet lot. And it assumes the contractor carries substantial liability insurance of their own, which any business should confirm in writing. The same attention to grounds that a commercial property needs in summer, the sort our seasonal maintenance crews provide, carries straight into a well run winter plan.
Putting a Plan in Place Before You Need It
The worst time to discover you have no snow removal plan is after the first fall. Commercial routes fill early, and a business scrambling for coverage in December is negotiating from weakness at exactly the moment reliability matters most. The plan should be in place, in writing, and understood by everyone before the season turns.
A well built snow removal plan is not an expense a business grudgingly accepts. It is risk management that quietly pays for itself the first time a claim is met with a complete, timestamped record instead of a shrug, and it protects the reputation of a property as much as its balance sheet. If you manage a commercial property and want that protection settled before winter, tell us about your site and we will scope a plan around it.